
Business & Finance
Commentary: Malaysia needs to restore foreign investors’ trust amid EV, data centre policy uncertainty
Key Points
Commentary: Malaysia needs to restore foreign investors’ trust amid EV, data centre policy uncertainty Malaysia's ability to attract foreign direct investment remains robust but the quality of the foreign capital could be compromised if domestic politics trump commercial logic, writes CNA’s Leslie Lopez. In 2024, Malaysia seemed to be the darling of Southeast Asian foreign investment. Tech giants - Google, Microsoft, Amazon, ByteDance - poured billions into data centres across Johor,...
Commentary: Malaysia needs to restore foreign investors’ trust amid EV, data centre policy uncertainty
Malaysia's ability to attract foreign direct investment remains robust but the quality of the foreign capital could be compromised if domestic politics trump commercial logic, writes CNA’s Leslie Lopez.
KUALA LUMPUR: In 2024, Malaysia seemed to be the darling of Southeast Asian foreign investment.
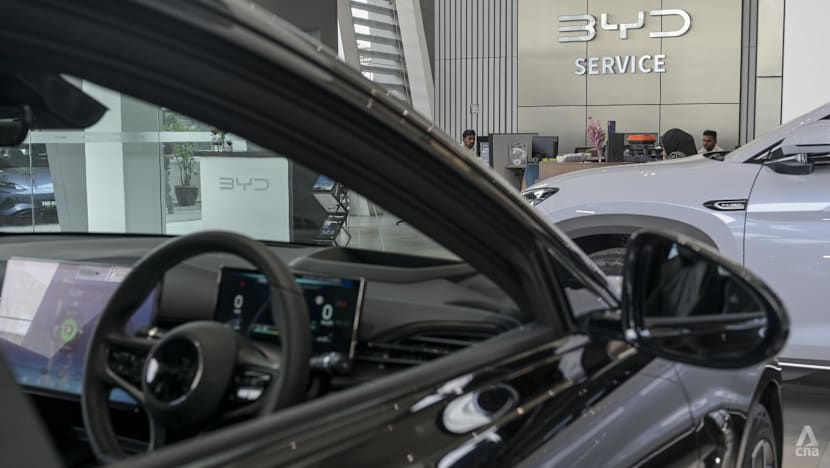
Tech giants - Google, Microsoft, Amazon, ByteDance - poured billions into data centres across Johor, transforming the sleepy Kulai corridor into one of Asia’s fastest-growing server farm hubs. Electric vehicle (EV) brands from BYD to Tesla rushed in, capitalising on a four-year blanket tax exemption on imported vehicles.
Approved foreign direct investment (FDI) hit a record RM207 billion (US$50.5 billion), and the message from Putrajaya seemed unambiguous: After years of political instability and policy drift, the Anwar Ibrahim administration was declaring that Malaysia was open for business.
Then the rules changed.
In December 2025, Malaysia’s EV import tax exemptions expired after four years, having been twice extended previously. By mid-2026, new restrictions slammed the brakes on affordable imported EVs, imposing a minimum import value of RM200,000 and power output thresholds that effectively screened out mass-market Chinese models.
Around the same time, the Malaysian government said it was rethinking how it attracts foreign investment as it acknowledged that it may have gone too far in rolling out incentives for data centre projects. In May, the government said it was stepping up scrutiny on the remaining unrealised data centre investments by filtering for high-quality industry players genuinely committed to operating in Malaysia.
To be sure, these policy changes have not yet derailed the headline numbers. According to the Malaysian Investment Development Authority (MIDA), approved investment reached RM218.5 billion in the first half of 2026, with foreign investment accounting for RM126.9 billion - roughly 58 per cent. The conveyor belt of economic announcements continues to hum.
But warning lights are flashing. The inconsistency on EVs and data centres is not merely the pragmatic recalibration of an emerging economy. It reflects how Malaysia manages foreign capital and it risks undermining investors’ confidence.
LACK OF PREDICTABILITY
The pattern is familiar. Generous incentives that can produce eye-catching investment announcements as well as political dividends. But when unintended consequences inevitably emerge - strained infrastructure, displaced local competitors or fiscal costs - the government changes course, sometimes abruptly, leaving investors holding the bag.
In an era when capital is mobile and alternatives abound, the result risks giving investors the impression that Malaysia's industrial policy is inconsistent.
Investors do not forget.
With each policy reversal, Malaysia’s risk premium rises - that invisible additional return investors demand to compensate for the possibility that the rules of engagement will shift beneath their feet.
Over time, this premium manifests not merely in higher financing costs but in the quality of investment the country attracts.
The danger is that capital becomes flightier, projects less capital-intensive, and companies structure Malaysian operations more as export platforms than as deeply integrated long-term commitments.
THREE MODELS, ONE REGION
Southeast Asia has long relied on FDI inflows as the engine of economic modernisation. But the region’s most successful economies have built their strategies on consistency, clarity and structural coherence. Malaysia, by contrast, appears to be improvising.
Consider the divergence in strategy across ASEAN’s major economies.
Singapore, unable to compete on labour costs and starved for land, long ago stopped trying to be a factory floor. Instead, it designed itself as the region’s command centre - hosting semiconductor headquarters, R&D hubs, commodity trading desks and wealth management towers.
Singapore generally permits 100 per cent foreign ownership across most sectors. It also has deep and liquid capital markets, and possesses an unwavering commitment to the rule of contract.
Thus, Singapore offers something Malaysia struggles to provide: predictability. Decision-makers locate there not because it is cheap, but because they trust the rules will not change after the ground is broken.
Indonesia, with a domestic market of 280 million people and sovereign control over the world’s largest nickel reserves, has pursued a markedly different but equally coherent path.
Jakarta has fused resource nationalism into industrial policy, demanding that foreign investors build battery plants, EV factories and smelters on Indonesian soil as the non-negotiable price of access to its minerals.
Thailand, decades ago, made a strategic bet on industrial depth. By nurturing local supply chains in automotive manufacturing and electronics, Bangkok created an ecosystem in which foreign investors became structurally embedded. Japanese automakers did not merely assemble cars in Thailand; they built a web of local parts suppliers, trained engineering talent and anchored regional procurement networks.
Malaysia, meanwhile, is stuck between models. It is too expensive to compete with Vietnam as a low-cost manufacturing hub. It lacks the domestic market scale and resource leverage of Indonesia. And it never achieved the supply-chain depth and institutional discipline that Thailand used to lock in long-term foreign commitment.
WHAT COMES AFTER THE HEADLINES
RM1.8 billion from BYD, RM20 billion from Google, RM10 billion from Microsoft, RM15 billion from ByteDance - these headline numbers also carry obvious political value, signalling competence and global confidence to a domestic audience.
But beyond the initial publicity blitz, what is the Anwar administration’s metric for investment success?
The EV and data centre episodes are telling.
In 2022, Malaysia unveiled a bold EV roadmap premised on a leisurely, decade-long transition for domestic automakers - primarily Proton and Perodua, which dominate the sub-RM100,000 vehicle segment. The policy offered duty-free imports to stimulate consumer familiarity and infrastructure building, with the implicit assumption that local players would have ample time to adapt before foreign competition reached the mass market.
The assumption proved wrong. Chinese manufacturers - BYD, Chery, GWM - rapidly mastered the mass production of competent EVs priced between RM50,000 and RM70,000, directly threatening not only Proton and Perodua but also the network of small and medium enterprises that supply them.
The policy had been designed for a gentle transition. The market delivered a shock.
New rules kicking in from July required imported EVs to carry a CIF (Cost, Insurance, and Freight) value of at least RM200,000 and a minimum power output of 180 kW - thresholds that effectively exclude many affordable Chinese models. Meanwhile, new completely knocked down (CKD) entrants are also required to export up to 80 per cent of locally assembled vehicles, with only 20 per cent allocated for the domestic market.
Media reports say BYD Malaysia will not proceed with plans in their original form to establish a completely knocked-down assembly plant in Tanjung Malim, Perak. The company added, however, that it is in discussions on local assembly cooperation and is looking for the best arrangement that fits in Malaysia’s automotive ecosystem. BYD’s experience illustrates some of the uncertainty confronting automakers.
A parallel drama is unfolding in Johor.
Google, Microsoft and a constellation of hyperscalers have planted billions in server farms across the Kulai industrial corridor, drawn by tax incentives, subsidised land and proximity to Singapore. The headlines were spectacular, but the infrastructure reality is less glamorous.
Data centres are voracious consumers of electricity and water. Malaysia’s national grid and water infrastructure are both already under strain.
THE POLITICAL CALCULUS
The core constraint on Malaysia's FDI strategy is political: Long-standing affirmative-action commitments and domestic constituencies can make major changes to industrial policy politically difficult.
The most consequential anchor is the Bumiputera equity policy, a centrepiece of Malaysian economic planning since the 1971 New Economic Policy (NEP).
Originally conceived as a 20-year affirmative-action programme, the NEP's legacy remains embedded in parts of Malaysia's economic and regulatory framework. Although foreign investors can own 100 per cent of businesses in many sectors, Bumiputera participation requirements and preferences continue to apply in particular regulated activities and government-linked opportunities.
Successive governments have understood that any serious attempt to dismantle or even dilute this edifice would trigger a political backlash.
Where Bumiputera participation requirements apply, they can constrain the ownership or partnership structures available to foreign investors. Critics argue that this can subordinate commercial considerations to political objectives.
THE LONG PRICE OF SHORT-TERMISM
The danger for Malaysia is not that FDI will dry up overnight.
The country continues to offer genuine competitive advantages: a multilingual workforce, decent infrastructure by regional standards, strategic geography along the Strait of Malacca, and a relatively open financial system. Capital will continue to flow, particularly into property, commodities, and low-margin assembly operations.
But the quality of that capital could degrade over time. Malaysia risks becoming a destination for footloose operations and attract the capital that seeks subsidies, not the capital that builds ecosystems.
The EV and data centre episodes should serve as a wake-up call.
If Malaysia wants to graduate from the region’s transactional waypoint to a genuine investment destination, it must do the hard, unglamorous work that its neighbours have already done: Build supply-chain depth, upgrade infrastructure and above all, restore the trust that is the single most valuable asset in the competition for global capital.